Affordable Health Insurance for Freelancers (2026): How to Find Quality Coverage Without Overspending
Affordable Health Insurance for Freelancers
Find affordable health insurance for freelancers. Compare plan types, costs, money-saving tips, and coverage options to choose the right policy in 2026.
affordable-health-insurance-for-freelancers
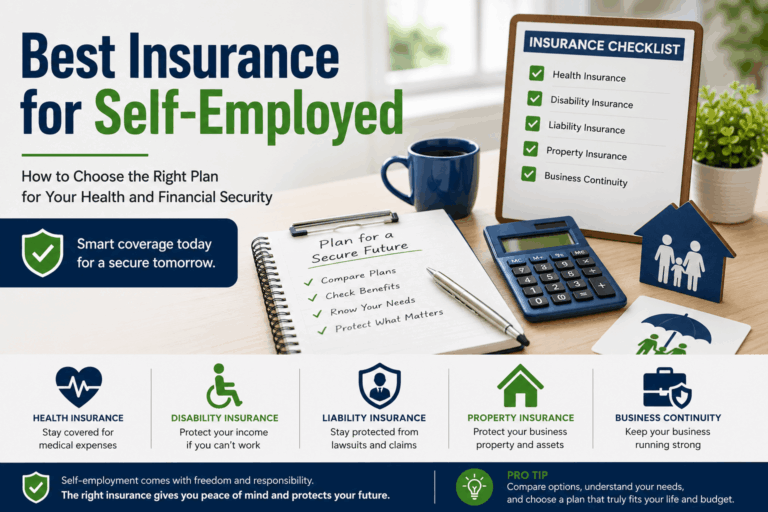
Freelancing gives you the freedom to choose your clients, set your schedule, and build a career on your own terms. However, one major challenge many freelancers face is finding affordable health insurance. Unlike traditional employees, freelancers usually don’t receive employer-sponsored health benefits, making it their responsibility to research, compare, and purchase coverage.
Whether you’re a full-time freelancer, self-employed consultant, independent contractor, designer, writer, or online entrepreneur, having health insurance can protect both your health and your finances. A single unexpected illness or accident could lead to thousands of dollars in medical bills without adequate coverage.
In this guide, you’ll learn how affordable health insurance for freelancers works, the different plan options available, ways to reduce your monthly costs, common mistakes to avoid, and practical tips for choosing the best policy for your needs.
Featured Snippet Definition
Affordable health insurance for freelancers refers to medical coverage designed for self-employed individuals who do not receive employer-sponsored benefits. Freelancers can purchase plans through government marketplaces, private insurers, professional associations, or eligible family coverage depending on their country and personal circumstances.
Why Health Insurance Matters for Freelancers
Being self-employed means you’re responsible for managing your own healthcare expenses. Medical emergencies can happen unexpectedly, and even routine care such as annual checkups or prescription medications can become expensive without insurance.
Health insurance helps by:
- Covering preventive healthcare
- Reducing out-of-pocket medical costs
- Providing financial protection during emergencies
- Offering access to a network of healthcare providers
- Supporting long-term health management
For many freelancers, insurance provides peace of mind that allows them to focus on growing their business rather than worrying about unexpected medical expenses.
Who Should Consider Freelancer Health Insurance?
Freelancer health insurance is suitable for people who earn income independently, including:
- Freelance writers
- Graphic designers
- Web developers
- Photographers
- Consultants
- Marketing professionals
- Ride-share drivers
- Online business owners
- Independent contractors
- Remote professionals
Even freelancers with part-time income should evaluate whether health coverage fits their needs.
Types of Health Insurance Available for Freelancers
Individual Health Insurance Plans
Individual health plans are purchased directly from insurance providers or government health insurance marketplaces where available.
These plans are often the most common option for freelancers because they are designed specifically for individuals and families.
Best for:
- Full-time freelancers
- Self-employed professionals
- Independent contractors
Marketplace Health Insurance Plans
Many countries offer government-supported health insurance marketplaces where eligible individuals can compare plans and determine whether they qualify for financial assistance based on household income.
These plans often include:
- Essential health benefits
- Preventive services
- Prescription drug coverage
- Emergency care
Depending on eligibility, premium assistance or subsidies may significantly reduce monthly costs.
Family Coverage
If your spouse or partner receives employer-sponsored health insurance, joining their family plan may be more affordable than purchasing an individual policy.
This option can simplify healthcare management while potentially lowering overall costs.
Short-Term Health Insurance
Short-term plans provide temporary coverage during transitions, such as:
- Starting freelancing
- Waiting for permanent insurance
- Temporary employment changes
However, these plans often have limited benefits and may not cover pre-existing conditions or preventive care.
Professional Association Plans
Some professional organizations and freelancer associations negotiate group health insurance benefits for members.
Although availability varies by country and organization, membership may provide access to competitive pricing or additional benefits.
What Does Freelancer Health Insurance Typically Cover?
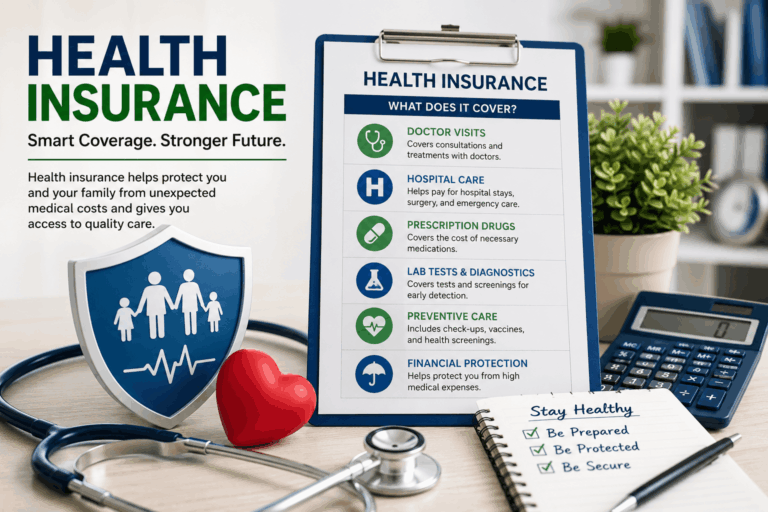
Coverage depends on the specific policy, but many comprehensive plans include:
- Doctor visits
- Preventive care
- Emergency services
- Hospital stays
- Laboratory testing
- Prescription medications
- Mental health services
- Maternity care (where included)
- Rehabilitation services
- Pediatric services for eligible family plans
Always review the policy documents carefully to understand covered services and exclusions.
Factors That Affect Health Insurance Costs
Several factors influence how much freelancers pay for health insurance.
Age
Older adults generally pay higher premiums because healthcare needs often increase with age.
Location
Healthcare costs differ between countries, regions, and even cities, affecting insurance pricing.
Plan Type
Plans with lower deductibles usually have higher monthly premiums, while higher-deductible plans often reduce monthly costs but increase out-of-pocket expenses.
Tobacco Use
Some insurers charge higher premiums for tobacco users, depending on local regulations.
Household Income
In some countries, income determines eligibility for government financial assistance or premium subsidies.
Family Size
Adding dependents usually increases monthly premiums but may reduce overall family healthcare expenses compared to separate plans.
How to Choose the Right Health Insurance Plan
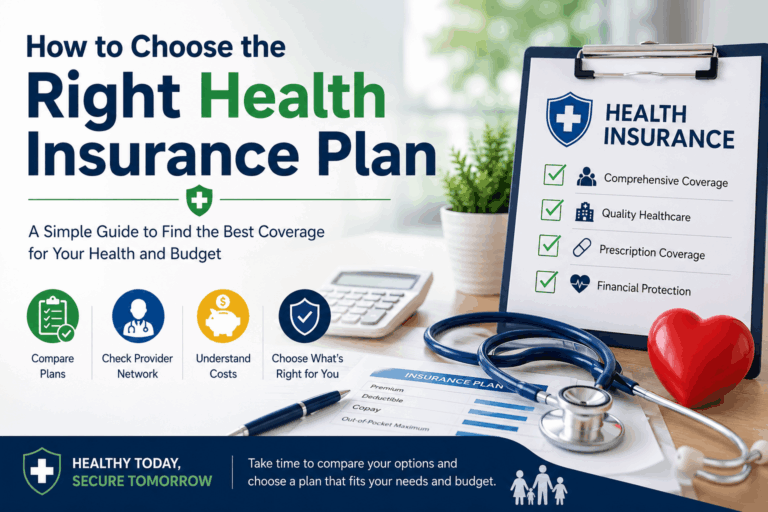
Choosing the cheapest policy isn’t always the best decision. Instead, compare the total value of each plan.
Consider the following:
Monthly Premium
This is the amount you pay each month regardless of whether you receive medical care.
Deductible
The deductible is the amount you generally pay before your insurance begins sharing covered healthcare costs.
Copayments and Coinsurance
These are the portions of healthcare costs you may pay after meeting your deductible, depending on your plan.
Provider Network
Check whether your preferred doctors, specialists, and hospitals participate in the insurer’s network.
Prescription Drug Coverage
If you take regular medications, review the plan’s drug coverage before enrolling.
Annual Out-of-Pocket Maximum
This limit helps protect you from extremely high healthcare costs during a policy year.
Comparison Table
| Monthly Cost | Moderate to Low (if eligible for assistance) | Varies | Often cost-effective | Usually lower |
| Comprehensive Coverage | Yes | Yes | Yes | Limited |
| Preventive Care | Included | Usually Included | Included | May Be Limited |
| Pre-existing Conditions | Generally Covered | Depends on local regulations | Usually Covered | May Not Be Covered |
| Long-Term Coverage | Yes | Yes | Yes | Temporary |
| Best For | Most freelancers | Self-employed professionals | Families | Temporary needs |
Ways Freelancers Can Save Money on Health Insurance
Compare Multiple Plans
Never purchase the first policy you see. Compare benefits, deductibles, provider networks, and overall value.
Check Financial Assistance
Depending on where you live and your household income, you may qualify for government subsidies or premium assistance.
Choose the Right Deductible
Healthy individuals who rarely visit doctors may benefit from higher deductibles and lower monthly premiums, while those expecting frequent medical care may prefer lower deductibles.
Use Preventive Care
Many comprehensive plans include preventive services at little or no additional cost. Regular checkups may help identify health issues early.
Stay In-Network
Using healthcare providers within your insurance network often reduces your overall medical expenses.
Real-World Example
Imagine Sarah, a freelance graphic designer who recently left a full-time job to start her own business. Initially, she focused only on finding the lowest monthly premium.
After comparing several plans, she realized that a slightly higher premium came with a much lower deductible, better prescription coverage, and access to her preferred healthcare providers. Although she paid a little more each month, her total healthcare costs ended up being lower because she needed regular specialist visits.
This example highlights why evaluating the overall value of a plan is often more important than choosing the cheapest option.
Best Practices When Shopping for Health Insurance
Review Coverage Every Year
Insurance plans, premiums, and benefits may change annually. Compare your options during each enrollment period.
Estimate Your Healthcare Needs
Think about:
- Regular prescriptions
- Planned surgeries
- Specialist visits
- Family healthcare needs
- Chronic conditions
This helps you choose an appropriate level of coverage.
Read the Policy Carefully
Understand:
- Coverage limits
- Waiting periods
- Exclusions
- Network restrictions
- Claim procedures
Knowing these details before enrolling can prevent surprises later.
Practical Tips
- Compare several insurers before making a decision.
- Balance monthly premiums with expected healthcare costs.
- Review deductibles, copayments, and out-of-pocket maximums together.
- Confirm your doctors and hospitals are in-network.
- Take advantage of preventive healthcare services.
- Keep digital copies of insurance documents.
- Review your plan annually as your income or healthcare needs change.
Common Mistakes
- Choosing a plan based only on the lowest premium.
- Ignoring deductibles and out-of-pocket costs.
- Not checking provider networks.
- Forgetting to compare prescription drug coverage.
- Missing enrollment deadlines.
- Assuming every plan covers the same services.
- Failing to review policy updates each year.
Key Takeaways
- Freelancers are responsible for arranging their own health insurance.
- Affordable coverage is available through marketplace plans, private insurers, family coverage, and some professional associations.
- Compare more than just monthly premiums before choosing a plan.
- Consider deductibles, provider networks, prescription coverage, and annual out-of-pocket limits.
- Preventive care and annual plan reviews can help reduce long-term healthcare expenses.
- Government financial assistance may be available to eligible individuals, depending on local regulations.
Frequently Asked Questions
1. Can freelancers get affordable health insurance?
Yes. Many freelancers can purchase individual health insurance through government marketplaces, private insurers, or eligible family plans. Costs depend on factors such as age, location, income, and the type of plan selected.
2. Is marketplace insurance better than private insurance?
It depends on your situation. Marketplace plans may offer financial assistance for eligible individuals, while private plans can provide different provider networks or additional coverage options.
3. What should freelancers compare before buying insurance?
Compare monthly premiums, deductibles, copayments, provider networks, prescription drug coverage, covered services, and annual out-of-pocket limits.
4. Can freelancers qualify for financial assistance?
In some countries, eligible individuals may qualify for premium subsidies or other financial assistance based on household income and local regulations.
5. Does health insurance cover preventive care?
Many comprehensive health insurance plans include preventive services such as annual wellness visits, vaccinations, and health screenings. Coverage varies by policy and country.
6. Should freelancers review their insurance every year?
Yes. Your healthcare needs, income, premiums, and available plans may change over time, making an annual review a smart financial decision.
Conclusion
Finding affordable health insurance for freelancers takes time, but it is one of the most important investments you can make for your health and financial security. Instead of focusing only on the lowest monthly premium, evaluate the complete value of each plan, including deductibles, provider networks, prescription coverage, and out-of-pocket costs.
By comparing multiple options, understanding your healthcare needs, and reviewing your policy annually, you can choose coverage that supports both your personal well-being and your freelance career. A well-informed decision today can help protect you from unexpected medical expenses and provide greater confidence as you continue building your business.
Disclaimer
This article is published solely for educational and informational purposes. The information provided is intended to increase general awareness and understanding of the topic. It should not be considered medical, insurance, financial, legal, or professional advice. Readers should consult qualified professionals before making any healthcare, insurance, financial, or legal decisions.
References
- HealthCare.gov
- U.S. Department of Health & Human Services (HHS)
- Centers for Medicare & Medicaid Services (CMS)
- Government of Canada
- National Health Service (NHS)
- Australian Government Department of Health, Disability and Ageing
- Citizens Advice (UK)
- MoneyHelper (UK)
- Irish Health Service Executive (HSE)
- Ministry of Health Singapore
- Mayo Clinic
- Cleveland Clinic