Best Insurance for Self-Employed: How to Choose the Right Plan
Best Insurance for Self-Employed | 2026 Guide
Find the best insurance for self-employed workers. Compare health coverage options, costs, benefits, and practical tips for choosing the right plan.
best-insurance-for-self-employed
Being self-employed gives you freedom, flexibility, and control over your work. However, it also means you may be responsible for finding and paying for your own insurance.
Unlike traditional employees, freelancers, consultants, independent contractors, gig workers, and small business owners may not receive health coverage or other benefits through an employer. That can make insurance decisions feel confusing, especially when income changes from month to month.
The best insurance for self-employed individuals is not always the plan with the lowest monthly premium. A cheaper plan may come with a high deductible, limited provider network, or higher out-of-pocket costs when you need medical care. On the other hand, paying for more coverage than you need can put unnecessary pressure on your business budget.
This guide explains the main insurance options available to self-employed workers, how to compare plans, what costs to consider, and how to choose coverage that fits your health needs, family situation, and financial goals.
What Is the Best Insurance for Self-Employed People?
The best insurance for self-employed people is a plan that provides suitable coverage at a manageable cost while protecting against major financial risks. For many U.S. freelancers and solo business owners, an individual Marketplace health plan may be a practical starting point. The right choice depends on income, location, household size, healthcare needs, and business structure.
Why Self-Employed Workers Need Insurance
Self-employment can create opportunities, but it also shifts many responsibilities from an employer to the individual.
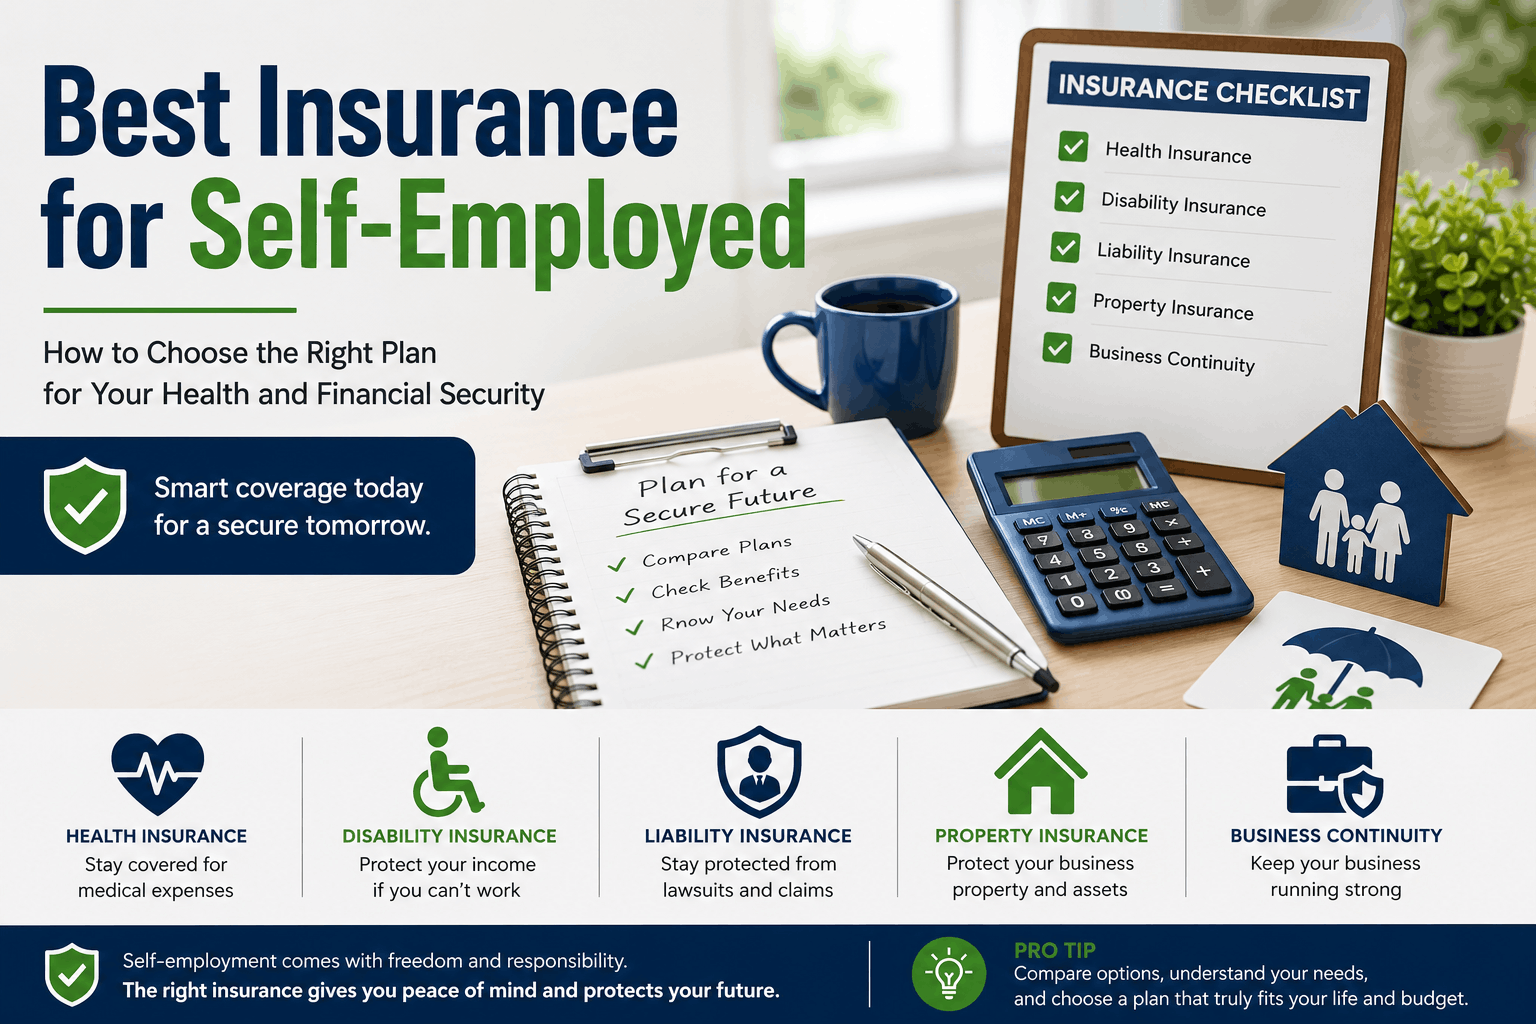
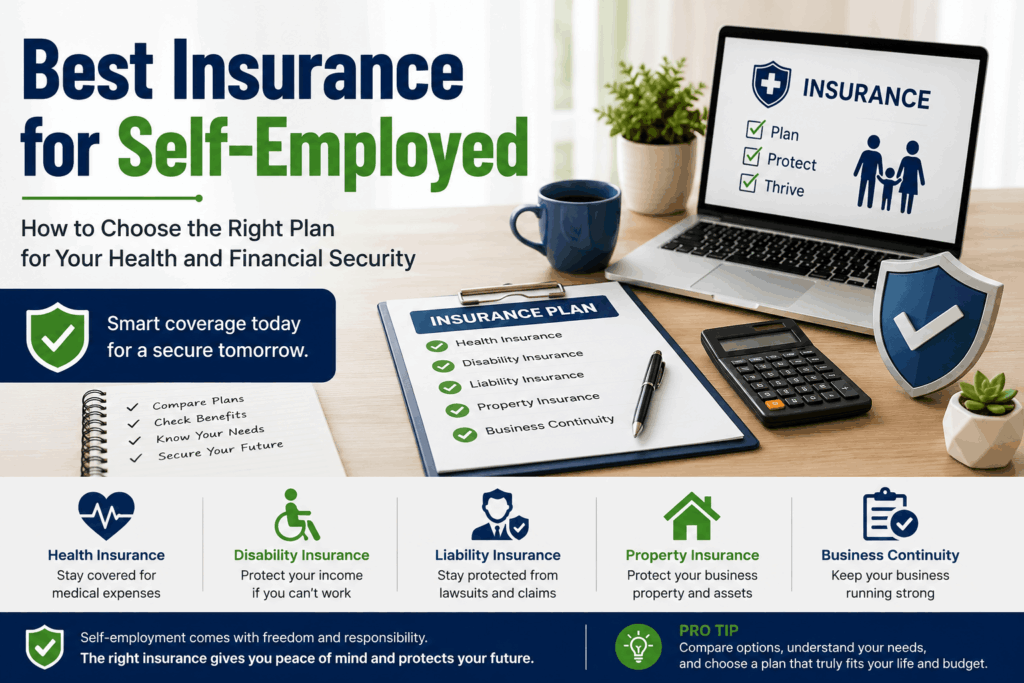
If you work for yourself, you may need to arrange your own health insurance, disability coverage, business protection, and other forms of insurance. Without proper coverage, an unexpected illness, injury, lawsuit, or business interruption could create significant financial pressure.
Insurance can help make major costs more predictable. It may also allow you to access healthcare services, protect business property, and reduce exposure to certain financial risks.
For example, imagine a freelance graphic designer who has a serious injury and cannot work for several months. Health insurance may help with eligible medical costs, while disability coverage may provide income protection if the policy terms are met.
The goal is not to buy every type of insurance available. The goal is to identify the risks that could seriously affect your health, income, family, or business.
Best Health Insurance Options for Self-Employed Workers
1. Individual Health Insurance Marketplace Plans
For many self-employed people in the United States, an individual Marketplace plan is one of the first options to consider.
If you are self-employed and have no employees, you can generally shop for individual and family coverage through the Health Insurance Marketplace. Depending on your income and household information, you may qualify for premium tax credits or other savings.
Marketplace plans are commonly grouped into metal categories:
- Bronze plans usually have lower monthly premiums but higher costs when you receive care.
- Silver plans generally offer a middle balance between premiums and out-of-pocket costs.
- Gold plans often have higher monthly premiums but lower costs when you use covered services.
- Platinum plans may have higher premiums and lower cost-sharing, although availability varies.
These categories are not quality ratings. They describe how costs are generally shared between the plan and the member.
A Marketplace plan may be useful if you want comprehensive coverage and the ability to compare plans in one place.
2. Private Individual Health Insurance
You may also be able to purchase health insurance directly from an insurance company or through a licensed insurance professional.
Private plans can offer different provider networks, plan designs, and pricing. However, it is important to confirm whether a policy provides comprehensive coverage and how it compares with Marketplace options.
Before enrolling, review:
- Monthly premium
- Annual deductible
- Copayments
- Coinsurance
- Out-of-pocket maximum
- Provider network
- Prescription drug coverage
- Coverage for specialists and hospitals
A private plan may be appropriate when it offers better access to preferred doctors or a plan structure that matches your needs.
3. Coverage Through a Spouse or Partner
If your spouse or partner has employer-sponsored health insurance, you may be eligible to join that plan.
This option can sometimes be simpler than purchasing separate coverage. However, compare the added premium with the cost and benefits of an individual plan.
Check whether your preferred doctors are included and whether the plan provides suitable coverage for the whole household.
4. Medicaid or Other Public Coverage
Some self-employed workers have variable or lower income, especially when starting a business.
Depending on income, household size, and local eligibility rules, you may qualify for Medicaid or another public health program. Eligibility and benefits vary by location.
Self-employed income may change during the year, so it is important to report accurate information and update your application when required. Marketplace savings are generally based on estimated net income for the coverage year.
5. Small Business Health Insurance
If you own a business with employees, small-group coverage may be available.
In the United States, the Small Business Health Options Program, commonly called SHOP, is designed to help eligible small employers provide health coverage to employees. Eligibility rules depend on factors such as business size and employee status.
A solo business owner with no employees generally uses individual coverage rather than SHOP.
Comparison Table: Self-Employed Insurance Options
| Marketplace health plan | Freelancers and solo business owners | Comprehensive coverage and possible income-based savings | Networks and costs vary by plan |
| Private individual plan | People seeking specific plan choices | May offer different networks or benefits | Compare carefully with Marketplace plans |
| Spouse’s employer plan | Couples and families | May simplify household coverage | Added premium may be expensive |
| Medicaid or public coverage | Eligible lower-income households | May provide low-cost or free coverage | Eligibility varies by location |
| Small-group business coverage | Owners with eligible employees | Can support employee benefits | Rules and employer costs apply |
How to Choose the Best Health Insurance Plan
Consider Your Monthly Budget
Start with the monthly premium, but do not stop there.
A plan with a low premium may have a high deductible. If you need frequent medical care, the lower premium may not produce the lowest total cost.
Estimate what you could reasonably afford during a normal month and during a year when you need more healthcare.
Review the Deductible
The deductible is generally the amount you pay for covered services before your plan begins paying certain costs.
A high-deductible plan may work for someone who rarely needs medical care and wants a lower monthly premium. However, it may be difficult to manage if an unexpected medical expense occurs.
Check the Out-of-Pocket Maximum
The out-of-pocket maximum is an important number because it helps show the most you may have to pay for covered in-network services during a plan year, subject to plan rules.
This can be especially important for self-employed workers who want protection against large healthcare expenses.
Check Your Doctors and Hospitals
A plan may look affordable but have a limited provider network.
Before enrolling, confirm whether your preferred primary care doctor, specialists, clinics, and hospitals participate in the plan.
Also check the rules for receiving care outside the network. Out-of-network costs can be much higher or may not be covered except in certain situations.
Review Prescription Drug Coverage
If you take regular medication, check the plan’s drug list, often called a formulary.
Look for:
- Whether the medication is covered
- Which cost tier applies.
- Whether prior authorization is required
- Whether quantity limits apply
- Which pharmacies are included
Other Important Insurance for Self-Employed People
Health insurance is often the priority, but it may not be the only coverage you need.
Disability Insurance
Disability insurance may provide benefits if an illness or injury prevents you from working and you meet the policy requirements.
Because self-employed income may stop when you cannot work, disability protection can be worth considering, particularly for people whose household depends heavily on their earnings.
Review the waiting period, benefit amount, benefit duration, exclusions, and definition of disability.
Professional Liability Insurance
Professional liability insurance, sometimes called errors and omissions insurance, may help protect certain professionals from claims related to mistakes, alleged negligence, or failure to deliver professional services.
It may be relevant to consultants, designers, accountants, technology professionals, and other service providers.
General Liability Insurance
General liability insurance may help cover certain claims involving bodily injury, property damage, or advertising-related issues.
It may be useful if clients visit your workplace or if your work involves customer property or public locations.
Business Property Insurance
If you own valuable equipment, inventory, tools, or office property, business property insurance may help protect against certain covered losses.
Review whether the policy covers equipment used outside your main business location.
Business Interruption Insurance
Business interruption coverage may help replace certain lost income or support eligible operating expenses after a covered event.
Coverage terms differ, so read the policy carefully.
Practical Tips for Finding Affordable Coverage
- Compare total yearly costs, not only monthly premiums.
- Estimate how often you expect to use healthcare services.
- Check whether your preferred doctors and hospitals are in-network.
- Review prescription coverage before enrolling.
- Keep business and personal insurance needs separate when appropriate.
- Update income information when required if your earnings change.
- Keep records of premiums and insurance documents.
- Review coverage every year because premiums, benefits, networks, and personal needs can change.
- Consider speaking with a licensed insurance professional if you need help understanding plan terms.
- Review tax rules with a qualified tax professional.
Tax Considerations for Self-Employed Health Insurance
In the United States, some eligible self-employed individuals may be able to deduct qualifying health insurance premiums, subject to IRS rules and limitations.
The IRS provides Form 7206 for calculating the self-employed health insurance deduction. Eligible premiums may include medical, dental, vision, and qualified long-term care coverage for the taxpayer, spouse, and dependents.
Tax treatment can depend on business income, business structure, other available coverage, and other factors. A deduction is not automatic, and it may not apply to every situation.
Because tax rules can change, review current guidance or consult a qualified tax professional.
Common Mistakes to Avoid
Choosing Only the Cheapest Premium
A low premium may look attractive, but the plan could have a high deductible or limited network.
Compare the full cost structure before making a decision.
Ignoring the Provider Network
Do not assume your doctor accepts every plan from the same insurance company.
Verify the exact plan network.
Forgetting About Prescription Costs
A plan may cover your medication but place it in a costly tier.
Check the formulary and expected pharmacy costs.
Underestimating Variable Income
Self-employed income may change throughout the year.
Use a realistic income estimate and update relevant information when required.
Buying Coverage Without Reading Exclusions
Insurance policies have limitations and exclusions.
Review what is covered, what is not covered, and what conditions apply to benefits.
Skipping Disability Protection
Many self-employed workers insure their health but do not consider how they would pay living expenses if they could not work.
Evaluate income protection based on your financial responsibilities and savings.
Key Takeaways
- The best insurance for self-employed workers depends on income, location, health needs, family size, and business risks.
- An individual Marketplace plan is a common option for U.S. freelancers and solo business owners.
- Compare premiums, deductibles, copays, coinsurance, provider networks, and out-of-pocket limits.
- Do not choose a plan based only on the lowest monthly premium.
- Self-employed workers may also need disability, liability, or business property insurance.
- Eligible U.S. taxpayers may be able to claim a self-employed health insurance deduction under applicable IRS rules.
- Review coverage regularly because insurance needs and plan details can change.
11. Frequently Asked Questions
What is the best health insurance for self-employed people?
The best health insurance depends on your income, location, household size, healthcare needs, and budget. For many U.S. self-employed workers, an individual Marketplace plan is a useful starting point because it allows plan comparison and may provide income-based savings for eligible applicants.
Can self-employed people get affordable health insurance?
Yes. Self-employed individuals may have access to Marketplace plans, private insurance, public programs, or coverage through a spouse’s employer. Eligibility for financial assistance depends on local rules and personal circumstances.
Is health insurance tax deductible for self-employed workers?
Some eligible self-employed individuals in the United States may be able to deduct qualifying health insurance premiums. IRS rules, income limits, business structure, and other coverage options can affect eligibility.
What insurance should a freelancer have?
Many freelancers consider health insurance first. Depending on the work performed, disability insurance, professional liability insurance, general liability insurance, and business property coverage may also be relevant.
Should self-employed people choose a high-deductible plan?
A high-deductible plan may be suitable for some people, particularly those who want lower monthly premiums and can manage higher costs when care is needed. It may not be the best choice for people who expect frequent medical services or have difficulty covering a large deductible.
Can a self-employed person get insurance through a spouse?
In many cases, yes. If a spouse has employer-sponsored coverage, the self-employed person may be eligible to join the plan. Compare the cost, network, and benefits with individual coverage.
How often should self-employed workers review insurance?
Review your coverage at least once a year and after major changes such as marriage, a new child, relocation, a major income change, or business expansion.
12. Conclusion
Finding the best insurance for self-employed workers is not about choosing the lowest premium or the most expensive plan. It is about matching coverage with your health needs, financial situation, family responsibilities, and business risks.
Start by comparing comprehensive health insurance options. Then look at the full cost of each plan, including the deductible, copays, provider network, prescription coverage, and out-of-pocket maximum.
If your business depends heavily on your ability to work, consider whether disability coverage could help protect your income. If you provide professional services or work with clients, evaluate liability coverage based on the risks involved.
Insurance decisions can affect both your personal finances and your business. Taking time to compare options carefully can help you choose coverage with greater confidence.
13. Disclaimer
This article is published solely for educational and informational purposes. The information provided is intended to increase general awareness and understanding of the topic. It should not be considered medical, insurance, financial, legal, or professional advice. Readers should consult qualified professionals before making any healthcare, insurance, financial, or legal decisions.
14. References
- U.S. Department of Health & Human Services (HHS)
- Centers for Medicare & Medicaid Services (CMS)
- HealthCare.gov
- Internal Revenue Service (IRS)
- Government of Canada
- National Health Service (NHS)
- Australian Government Department of Health, Disability and Ageing
- Government of New Zealand
- Citizens Information Ireland
- Ministry of Health Singapore