What Is Health Insurance? A Complete Beginner’s Guide (2026)
Learn what health insurance is, how it works, the different plan types, key terms, costs, and tips to choose the right coverage in this complete 2026 beginner’s guide.
what-is-health-insurance-guide-2026
Imagine waking up with severe chest pain or breaking a bone in an unexpected accident. Without health insurance, even a short hospital visit could lead to thousands of dollars in medical bills. For many individuals and families, these unexpected healthcare costs can create significant financial stress.
Health insurance helps reduce that burden by sharing the cost of medical care between you and your insurance provider. Whether you need routine checkups, emergency treatment, prescription medications, or preventive care, the right health insurance plan can make healthcare more affordable and accessible.
If you’re new to health insurance, the terminology and plan options may seem confusing. Terms like premiums, deductibles, copayments, and provider networks often leave first-time buyers with more questions than answers.
This beginner-friendly guide explains everything you need to know in simple language. You’ll learn how health insurance works, the different types of plans available, what they typically cover, common insurance terms, and practical tips for choosing a policy that fits your needs in 2026.
What Is Health Insurance? (Featured Snippet)
Health insurance is a contract between you and an insurance company that helps pay for eligible medical expenses. In exchange for a monthly premium, the insurer shares the cost of covered healthcare services, such as doctor visits, hospital stays, prescription drugs, preventive care, and emergency treatment, as outlined in your policy.
What Is Health Insurance?
Health insurance is designed to protect you from high healthcare costs. Instead of paying the full price for every doctor’s appointment, surgery, or prescription, you pay a portion while your insurance company pays the remaining covered amount.
Think of health insurance as a financial safety net. You contribute a regular monthly payment called a premium, and in return, your insurance provider helps cover eligible medical expenses when you need healthcare services.
Health insurance does not eliminate healthcare costs entirely, but it can significantly reduce what you pay out of pocket.
Why Is Health Insurance Important?
Healthcare expenses continue to rise in many countries, especially in the United States. Even routine medical care can become expensive without insurance.
Health insurance offers several important benefits:
Protects Your Finances
Unexpected illnesses or accidents can result in medical bills worth hundreds or even thousands of dollars. Insurance helps reduce these costs and prevents many families from facing financial hardship.
Encourages Preventive Care
Many insurance plans cover preventive services such as:
- Annual health checkups
- Vaccinations
- Blood pressure screenings
- Cholesterol tests
- Cancer screenings
Detecting health problems early often leads to better outcomes and lower treatment costs.
Improves Access to Healthcare
People with health insurance are generally more likely to visit healthcare professionals regularly, receive recommended treatments, and fill necessary prescriptions.
Provides Peace of Mind
Knowing that you’re financially protected during medical emergencies allows you to focus on recovery rather than worrying about unexpected bills.
How Does Health Insurance Work?
Understanding the basic process makes health insurance much less intimidating.
Step 1: Pay a Monthly Premium
You pay a fixed monthly amount to keep your insurance policy active.
This payment is required whether or not you use healthcare services.
Step 2: Receive Medical Care
When you become sick, injured, or need preventive care, you visit a healthcare provider that accepts your insurance.
Step 3: Insurance Shares the Cost
Depending on your policy, you may pay part of the cost while your insurance company pays the remaining covered amount.
The amount each party pays depends on your:
- Deductible
- Copayment
- Coinsurance
- Out-of-pocket maximum
Common Health Insurance Terms Explained
Understanding a few key terms makes choosing a plan much easier.
Premium
A premium is the monthly amount you pay to keep your insurance coverage active.
Example:
If your premium is $350 per month, you’ll pay that amount every month regardless of whether you visit a doctor.
Deductible
A deductible is the amount you pay for covered healthcare services before your insurance begins paying its share.
Example:
If your deductible is $1,500, you’ll generally pay the first $1,500 of eligible medical expenses before the insurance company starts contributing, subject to your plan’s rules.
Copayment (Copay)
A copay is a fixed amount you pay for certain healthcare services.
For example:
- $25 for a primary care visit
- $50 for a specialist
- $15 for many generic prescriptions
The insurance company pays the remaining covered cost.
Coinsurance
Coinsurance is the percentage of healthcare costs you share with your insurer after meeting your deductible.
Example:
If your plan has 20% coinsurance, you pay 20% of covered costs while the insurance company pays 80%.
Out-of-Pocket Maximum
This is the maximum amount you pay for covered services during a plan year.
Once you reach this limit, your insurance generally pays 100% of covered healthcare costs for the remainder of the year, according to your policy.
What Does Health Insurance Usually Cover?
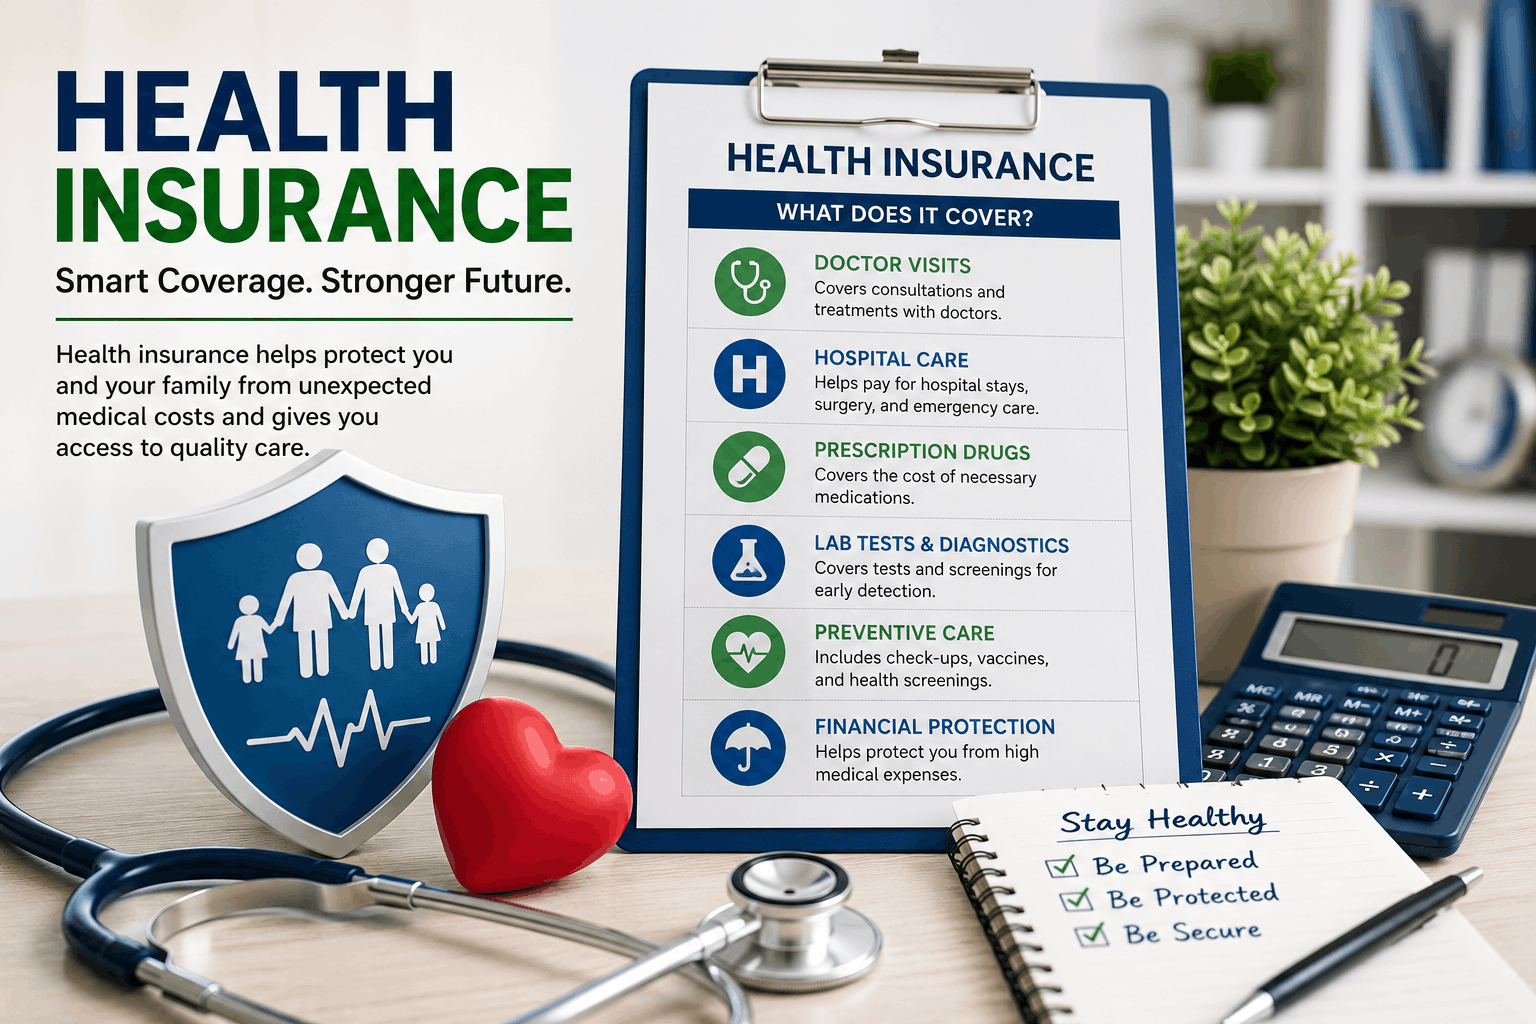
Coverage varies by plan, but many policies include:
Preventive Care
Preventive services often include:
- Wellness visits
- Routine screenings
- Immunizations
- Health counseling
Many preventive services are covered with little or no additional cost when received according to plan rules.
Doctor Visits
Coverage usually includes:
- Primary care appointments
- Specialist consultations
- Follow-up visits
Hospital Care
Most comprehensive plans help cover:
- Emergency room treatment
- Hospital admissions
- Surgery
- Intensive care
- Overnight stays
Prescription Medications
Many insurance plans cover prescription drugs through a formulary, although the amount you pay depends on the medication and your specific plan.
Types of Health Insurance Plans
Different health insurance plans offer different levels of flexibility, provider choice, and costs. Understanding these options can help you choose the plan that best fits your healthcare needs and budget.
Health Maintenance Organization (HMO)
An HMO plan generally requires you to choose a primary care physician (PCP). Your PCP coordinates your care and usually provides referrals if you need to see a specialist.
Pros
- Lower monthly premiums
- Lower out-of-pocket costs
- Coordinated care
Cons
- Limited provider network
- Referrals often required for specialists.
- Less flexibility when traveling
Preferred Provider Organization (PPO)
PPO plans offer more flexibility. You can usually see specialists without a referral and may receive partial coverage for out-of-network care.
Pros
- Greater provider choice
- No referral required for specialists
- Better for people who travel frequently
Cons
- Higher premiums
- Higher deductibles in many cases
Exclusive Provider Organization (EPO)
An EPO combines features of HMO and PPO plans. You typically do not need referrals, but you must use providers within the network except during emergencies.
Pros
- No referrals
- Lower premiums than many PPO plans
Cons
- No coverage for most out-of-network care
Point of Service (POS)
POS plans require a primary care physician but allow some out-of-network care at a higher cost.
Pros
- Coordinated healthcare
- Some flexibility outside the network
Cons
- Referrals often required
- More paperwork for out-of-network claims
Comparison Table
| HMO | Yes | Usually Yes | Rarely | Budget-conscious individuals |
| PPO | No | No | Yes | Maximum flexibility |
| EPO | No | No | Emergencies only | Lower costs with flexibility |
| POS | Yes | Usually Yes | Limited | Families wanting coordinated care |
How to Choose the Right Health Insurance Plan
There is no single plan that works for everyone. Consider these factors before making your decision.
Evaluate Your Healthcare Needs
Ask yourself:
- Do you visit doctors frequently?
- Do you take prescription medications?
- Do you have a chronic medical condition?
- Are you planning surgery or maternity care?
Your expected healthcare needs can help determine whether a lower-premium or more comprehensive plan is a better fit.
Compare Total Costs
Don’t focus only on the monthly premium.
Also compare:
- Deductible
- Copayments
- Coinsurance
- Out-of-pocket maximum
Sometimes a plan with a higher monthly premium can cost less overall if you expect to use healthcare services frequently.
Check the Provider Network
Make sure your preferred:
- Primary care doctor
- Specialists
- Hospitals
- Pharmacies
Are included in the insurance network.
Review Covered Benefits
Read the policy carefully to understand what is covered and what may require additional costs or approvals.
Practical Tips
- Compare several plans before enrolling.
- Read the Summary of Benefits and Coverage carefully.
- Verify that your doctors and hospitals are in-network.
- Understand your deductible before choosing a low-premium plan.
- Take advantage of preventive care services that may be covered.
- Keep copies of insurance documents and medical bills.
- Review your coverage each year during open enrollment, as plans and costs can change.
Common Mistakes
Many first-time buyers make avoidable mistakes when selecting health insurance.
Choosing Based Only on Premium
A low monthly premium may come with a high deductible and higher overall costs if you need medical care.
Ignoring the Provider Network
Your preferred doctor may not accept every insurance plan. Always check before enrolling.
Not Understanding Key Terms
Knowing the difference between premiums, deductibles, copays, and coinsurance helps you estimate your true healthcare costs.
Skipping Preventive Care
Routine screenings and wellness visits can help detect health problems early and may be covered under your plan.
Missing Enrollment Deadlines
Some insurance plans only allow enrollment during specific periods unless you qualify for a special enrollment event.
Key Takeaways
- Health insurance helps reduce the financial impact of medical expenses.
- You pay a monthly premium to maintain coverage.
- Understanding deductibles, copayments, coinsurance, and out-of-pocket limits is essential.
- Different plan types offer different levels of flexibility and cost.
- Comparing total costs—not just premiums—can help you choose the best plan.
- Reviewing provider networks and covered services before enrolling can prevent unexpected expenses.
- Choosing the right health insurance is an important step toward protecting both your health and your finances.
Frequently Asked Questions
1. What is health insurance in simple terms?
Health insurance is an agreement in which an insurance company helps pay eligible medical expenses in exchange for a monthly premium and other applicable cost-sharing.
2. Is health insurance worth it?
For many people, health insurance provides valuable financial protection against unexpected healthcare costs and improves access to preventive and routine medical care.
3. What is the difference between a premium and a deductible?
A premium is the amount you pay each month to keep your policy active. A deductible is the amount you generally pay for covered services before your insurance starts sharing costs.
4. Can I visit any doctor with health insurance?
It depends on your plan. Some plans limit you to a network of providers, while others offer partial coverage for out-of-network care.
5. What services are commonly covered?
Many plans include preventive care, doctor visits, hospital care, emergency services, prescription medications, laboratory tests, and certain mental health services. Coverage varies by policy.
6. Does health insurance cover emergencies?
Most comprehensive health insurance plans include coverage for emergency medical care, although your share of the cost depends on your policy’s terms.
Conclusion
Health insurance can seem complicated at first, but understanding the basics makes it much easier to make informed decisions. Knowing how premiums, deductibles, copayments, and provider networks work allows you to compare plans with confidence and avoid unexpected costs.
Whether you’re buying health insurance for the first time, changing jobs, or reviewing your coverage during open enrollment, taking the time to understand your options can help you choose a plan that supports both your healthcare needs and your financial well-being. While no policy covers every situation, the right health insurance can provide valuable peace of mind and better access to quality medical care when you need it most.
Disclaimer
This article is published solely for educational and informational purposes. The information provided is intended to increase general awareness and understanding of the topic. It should not be considered medical, insurance, financial, legal, or professional advice. Readers should consult qualified professionals before making any healthcare, insurance, financial, or legal decisions.
References
- World Health Organization (WHO)
- Centers for Medicare & Medicaid Services (CMS)
- HealthCare.gov
- U.S. Department of Health & Human Services (HHS)
- Centers for Disease Control and Prevention (CDC)
- National Health Service (NHS)
- Government of Canada
- Australian Government Department of Health and Aged Care
- Mayo Clinic
- Cleveland Clinic
Author Information
Reviewed by: bobevansmenu Editorial Team
Content Type: Educational Health Content
Last Updated: July 2026